Think of it as Yoga for the brain, we are going to stretch a bit.
How the Rich Avoid Paying Income Tax — and You Can Too
Do you want to be rich or poor? The real answer will surprise you -- YNOT!
You have to change your mindset.
Stop thinking about income. Start thinking about growth.
Most of us are taught one financial model from childhood:
Go to school. Get a job. Earn more money. Get a raise. Earn even more money.
And we measure success by income.
$75,000 a year.
$150,000 a year.
$500,000 a year.
But there is a problem with income. Income gets taxed.
The more you earn, particularly as wages or salary, the more of your economic life runs through the income-tax system.
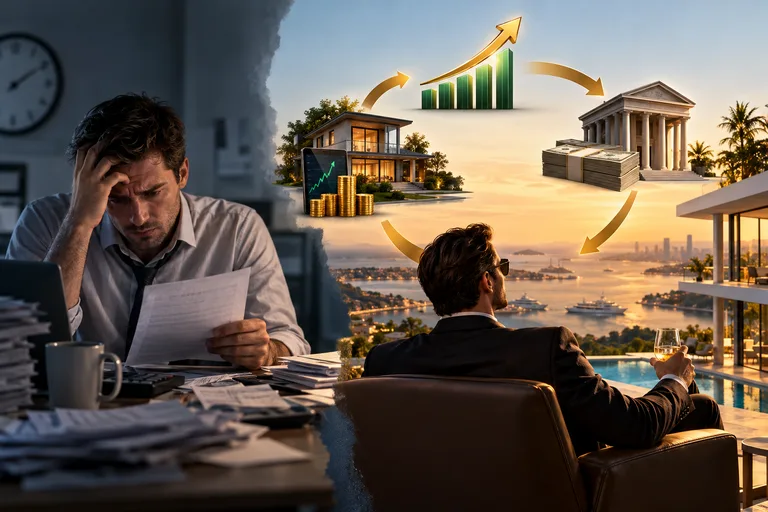
The very wealthy often play a different game.
They aren’t necessarily asking: “How can I earn another $1 million this year?”
They’re asking:“How can I increase the value of the assets I already own by another $10 million?”
Those are two very different questions.
And understanding that difference changes the way you think about money.
The rich don’t primarily pursue income. They pursue ownership.
Suppose you earn $200,000 working. That’s income.
Taxes become due according to the rules governing that income.
Now suppose instead you own a business worth $2 million and, over several years, it grows to $3 million.
You have become $1 million wealthier.
But you haven’t necessarily received $1 million of taxable income.
The value of something you own increased.
The same principle applies to stocks.
Buy stock for $100,000. Years later it’s worth $300,000. Your net worth increased by $200,000. But as long as you haven’t sold it, you generally haven’t realized that $200,000 capital gain.
That distinction is enormous.
And it leads to one of the most important wealth-building ideas I think ordinary investors should understand:
YOU DON’T HAVE TO SELL AN ASSET TO GET MONEY FROM IT.
You can sometimes borrow against it. That’s the part people miss.
Imagine you own $1 million of appreciating assets.
They might be:Stocks. Real estate. A business. Investment property. Or some combination of them.
You need $50,000.
The conventional approach is: Sell $50,000 of assets.
But selling may create a taxable capital gain. You also lose ownership of whatever you sold, along with its potential future appreciation.
The wealthy frequently consider another possibility:
Keep the asset and borrow against it.
The asset becomes collateral.
You receive cash from the lender.
And because a legitimate loan has to be repaid, the borrowed money itself generally isn’t taxable income.
That’s the mindset shift. Don’t destroy the asset to extract value from the asset.
Use the asset.
Think about your house.
Millions of ordinary Americans already understand this principle without realizing they’re using the same basic concept.
Imagine buying a house for $300,000. Years later it’s worth $600,000.
You didn’t receive a $300,000 paycheck. The asset appreciated.
If you need liquidity, one possibility is selling the house.
But another possibility may be borrowing against some of the equity.
You still own the house. If it continues appreciating, you still participate in that appreciation.
The loan gives you liquidity without requiring you to sell the underlying asset.
Real-estate investors do variations of this constantly.
Buy property. Improve it. Increase its value. Build equity. Refinance.
Use some of that capital to acquire another asset. Repeat.
The objective isn’t necessarily to produce the biggest paycheck possible.
The objective is to control an increasingly valuable collection of assets.
The same principle exists in investment portfolios.
People with substantial brokerage portfolios may have access to securities-backed lines of credit or other forms of collateralized borrowing.
The philosophy is simple: My portfolio isn’t just something I can sell. My portfolio is financial collateral.
That is a completely different way of looking at wealth.
Someone with $5 million invested doesn’t necessarily need to liquidate $200,000 of investments every time they need $200,000.
Under the right circumstances, they may borrow against part of the portfolio instead.
So the asset remains invested. No sale occurred merely because the loan was made.
And therefore the act of borrowing itself generally doesn’t create the capital-gains event that selling appreciated securities might create.
This is one reason the financial lives of the very wealthy can look so different from those of high-income employees.
A high-income person can still be trapped in the income system.
Imagine two people. One makes $500,000 every year but spends nearly all of it.
The other owns $10 million in businesses, property and investments that appreciate over time.
Who is richer? Obviously the second person.
Yet we remain obsessed with income. That’s the wrong scoreboard.
Income measures what came through the door.
Wealth measures what you own. And ownership is where compounding happens.
That’s why my preferred mental model is:
BUILD → GROW → BORROW → KEEP GROWING.
Build assets. Let the assets appreciate.
Don’t automatically sell every time you need liquidity.
Where financially sensible, borrow conservatively against assets rather than liquidating them.
And allow compounding to continue.
There is an even longer-term component.
Think generationally.
Under current U.S. tax law, inherited assets generally receive a new tax basis based on their value around the owner’s death, subject to numerous rules and exceptions.
This is the famous “step-up in basis.”
Imagine somebody bought an investment decades ago for $100,000.
At death it is worth $1 million. That’s $900,000 of appreciation.
Under the general inherited-basis rule, the heir’s basis may become approximately the asset’s fair market value at death rather than the original $100,000 purchase price.
That can dramatically reduce the capital gain that would otherwise exist if the original owner sold the asset during life.
This is where the phrase comes from:
BUY. BORROW. DIE.
It sounds cynical. But it describes an important part of how America’s wealth and tax systems interact.
BUY appreciating assets. BORROW carefully against those assets rather than automatically selling them.
DIE owning the assets and transfer them according to a properly constructed estate plan.
And here’s the part I want ordinary people to understand:
You don’t have to be a billionaire to learn from this.
You may not have Jeff Bezos’ stock portfolio.
That isn’t the point. The principle scales down.
Your version might be: A $100,000 investment portfolio.
A rental property. Your home. A small business. A 401(k). An IRA.
A piece of commercial property.
A portfolio of dividend-producing investments.
Or equity in a company you’re building.
The objective should increasingly become:
Acquire productive and appreciating assets instead of simply acquiring things that consume income.
That changes the questions you ask.
Instead of: “How much can I afford to spend?”
Ask: “What can I buy that will make me wealthier ten years from now?”
Instead of: “How big a paycheck can I get?”
Ask: “How much ownership can I accumulate?”
Instead of: “I need cash, what can I sell?”
Ask: “Do I actually need to sell this asset, or can I obtain liquidity another way?”
And instead of measuring your success entirely by income:
Measure your net worth and the productive capacity of your assets.
But there is a warning.
BORROWING IS NOT FREE MONEY.
This is where internet financial gurus get dangerous.
Debt has interest. Interest rates change. Real estate can fall. Stocks can crash.
Businesses can fail. A securities-backed loan can become extremely dangerous if the collateral plunges in value.
Borrow too aggressively against a stock portfolio and a market crash can force you to sell exactly when you least want to sell.
Borrow too much against real estate and a recession, vacancy problem or refinancing crisis can destroy you.
And personal borrowing costs may not be tax deductible.
So the lesson isn’t: Borrow everything you possibly can.
The lesson is: Understand the difference between debt used against productive assets and debt used simply to consume.
A billionaire borrowing 5% against an enormous diversified asset base is in a fundamentally different position from someone borrowing 80% against a volatile portfolio to pay household expenses.
The mathematics matter. The collateral matters. Cash flow matters. Interest rates matter.
Liquidity matters. Diversification matters. And taxes are only one part of the decision.
Sometimes selling and paying the tax is absolutely the smarter choice.
So when I say, “Never sell. Borrow,” I’m describing a mindset — not an absolute rule.
The better rule is:Don’t sell appreciating assets unnecessarily.
Make selling a deliberate financial decision instead of your automatic source of cash.
Because the people who become truly wealthy generally don’t become wealthy because they received the world’s largest paycheck.
They become wealthy because they owned something that became extremely valuable.
A company. Real estate. Stocks. Intellectual property. Land. Investments. Ownership created the fortune.
And once they had the fortune, they structured their financial lives around preserving ownership.
That is the lesson worth learning.
The tax code isn’t merely about how much money you make.
It cares enormously about HOW you make it.
Salary. Business income. Dividends. Interest. Capital gains. Unrealized appreciation. Borrowed money. Inheritance.
These are not treated identically.
Financial literacy means understanding those differences and using them legally and intelligently.
So change the mindset.
Don’t spend your entire life trying to maximize income. Maximize ownership.
Build assets. Let them compound.
Use debt conservatively and strategically when it makes economic sense.
Sell intentionally rather than automatically.
And build something that can continue growing long after today’s paycheck is gone.
Because eventually the goal isn’t:
“How much money do I make?”
The goal becomes: “How much do I own — and how fast is it growing?”
That is how wealthy people think.
And you can learn to think that way too.
——-
This is a discussion of financial and tax strategy, not individualized tax, investment, lending, or estate-planning advice. The details matter enormously, particularly with leveraged investments, trusts, retirement accounts and estate planning. Use a CPA, tax attorney and qualified financial adviser before implementing significant borrowing or tax strategies.