Think of it as Yoga for the brain, we are going to stretch a bit.
Capitalism Doesn’t Reward Hard Work. It Rewards Leverage.
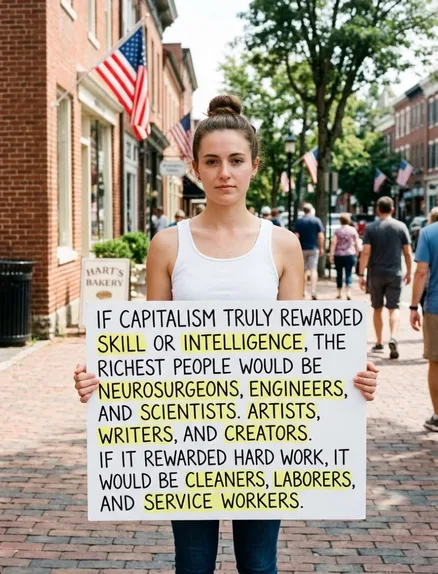
If capitalism truly rewarded skill or intelligence, the richest people would be neurosurgeons, engineers, scientists, artists, writers and creators. If it rewarded hard work, it would be cleaners, laborers and service workers. -- Some Random person on Internet

Capitalism Doesn’t Reward Hard Work. It Rewards Leverage. -- YNOT!
I saw this graphic above making the rounds:
It sounds profound.
But it misunderstands what capitalism actually rewards.
Capitalism does not have a scoreboard for intelligence, effort, education, suffering, or how physically exhausted you are at the end of the day.
The market primarily rewards value that can be exchanged, multiplied, owned and scaled.
That distinction matters.
A brilliant neurosurgeon might save somebody’s life. That’s enormous value. But the surgeon can only perform so many operations personally.
A cleaner might work harder physically than almost anyone in the building. But one person can only clean so many rooms.
An engineer might be extraordinarily intelligent. But if that engineer works for someone else, much of the economic leverage created by that intelligence belongs to the organization employing them.
Then somebody creates a piece of software used by 100 million people.
They write it once. It gets sold 100 million times. That’s leverage.
Someone builds a company employing 20,000 people. That’s leverage.
Someone invents a product, owns the patent, organizes the manufacturing, finds the financing, creates the distribution system and assumes the risk of bringing it to market.
That’s leverage combined with ownership and execution.
And that’s the part these arguments usually leave out.
Hard work matters. Intelligence matters. Skill matters.
But they’re ingredients. They aren’t the finished product.
I’ve known extremely intelligent people who couldn’t organize a two-car parade.
I’ve also known people who weren’t the smartest person in the room but could recognize an opportunity, assemble the right people, make decisions, take calculated risks and actually get something accomplished.
Guess which person usually creates the successful business?
The market doesn’t ask: “How hard did you work?”
It asks: “What did you produce that somebody else wants, and how many people can you provide it to?”
There’s another uncomfortable component:
Ownership matters.
If you dig a ditch for $25 an hour, you get paid for digging the ditch.
If you own the company with 100 people digging ditches, you participate economically in the output of all 100.
That doesn’t automatically mean the owner deserves every dollar or that every economic outcome is fair.
It simply explains the mechanics. Ownership creates leverage. Capital creates leverage.
Technology creates leverage. Employees create leverage. Distribution creates leverage.
Intellectual property creates leverage. AI is becoming an enormous form of leverage.
And risk creates the opportunity to own that leverage.
Most businesses fail. Someone usually invested money, time or years of their life before knowing whether customers would ever show up.
When the business succeeds, we’re very good at seeing the reward.
We’re much worse at remembering the risk that existed before the outcome was known.
This is also why “work harder” is terrible business advice.
You only have 24 hours in a day. There is a physical ceiling on effort.
The better question is: How do I make each hour produce more?
Can software automate it? Can AI multiply it?
Can someone else be trained to do it? Can the process be standardized?
Can the product be sold repeatedly? Can you own the thing you’re creating instead of continually selling your time?
That’s where Measure Twice, Cut Once enters the equation.
Thinking is leverage too. Spending an hour designing the right process can eliminate 100 hours of future labor.
Spending a day understanding a market can prevent a $100,000 mistake.
Building the correct system once may eliminate years of repetitive work.
The carpenter who swings the hammer hardest isn’t necessarily the best carpenter.
The best carpenter figures out where the nail needs to go before swinging the hammer.
So no, capitalism doesn’t reliably reward the smartest people.
It doesn’t reliably reward the hardest-working people either.
It rewards some combination of: Value + Scarcity + Execution + Ownership + Risk + Scale + Leverage.
Skill and hard work can contribute enormously to all seven.
But confusing effort with economic value is a mistake.
And understanding that distinction may be one of the most important lessons anyone can learn about business.
Don’t just work harder. Build something that makes your work multiply.
The Biggest Fortunes Are Built by Stacking Leverage
Look at people such as Elon Musk, Michael Dell and Jeff Bezos.
None of them became extraordinarily wealthy because they personally worked 10,000 times harder than everyone else.
They became extraordinarily wealthy because they learned how to stack leverage on top of leverage.
They leverage money, people, relationships, technology, information, distribution and ownership simultaneously.
Michael Dell didn’t become wealthy by personally assembling more computers than everyone else. Dell built a system that could sell, manufacture, finance and distribute computers at enormous scale. Once the machine existed, thousands of employees, suppliers, factories and dollars of working capital were all producing on his behalf.
Jeff Bezos didn’t become wealthy because he could personally pack boxes faster than a warehouse worker. Amazon became powerful because Bezos combined software, warehouses, logistics, capital, customer data, suppliers and millions of customers into one enormous machine.
Then every new advantage strengthened the others.
More customers attracted more sellers. More sellers created more selection.
More selection attracted more customers. More volume justified better logistics.
Better logistics made Amazon more attractive.
And greater scale made raising and investing additional capital easier.
That’s compounding leverage.
Elon Musk provides another interesting example. Tesla and SpaceX require extraordinary amounts of engineering talent, manufacturing capacity, capital and technology. Musk doesn’t design every circuit board, weld every rocket or write every line of software himself.
He organizes and controls systems containing thousands of intelligent people, billions of dollars of equipment, intellectual property, factories, computers and accumulated knowledge.
Then there is another form of leverage that successful people acquire: Connections.
Once you have a reputation, capital and a network, opportunities start coming to you.
The entrepreneur starting their first company may spend six months trying to get a meeting with an investor.
Someone who has already built a billion-dollar company can make a few phone calls.
That’s leverage too. And leverage compounds.
Money creates access. Access creates opportunities. Opportunities create information.
Information improves decisions. Successful decisions attract more money.
That doesn’t mean every wealthy person succeeds or that every investment works.
It means they are playing with a very different-sized lever.
AI Is Giving Ordinary People a Lever They Never Had Before
This is where I think AI changes the equation dramatically.
Historically, one of the greatest forms of leverage was having people who knew things you didn’t know.
Large companies could afford accountants, programmers, lawyers, researchers, graphic designers, marketing departments, analysts and consultants.
A small business owner couldn’t.
Now imagine one entrepreneur sitting at a computer with AI.
They can say: “Analyze these 10 competitors and explain their pricing strategies.”
Twenty minutes later they have research that might once have taken an employee days.
Or: “Read this 3,000-line program, find the bug and explain how to fix it.”
Or: “Take these sales figures and identify which customers are becoming less profitable.”
Or: “Design the database architecture for this application before I start programming it.”
Or: “Give me 20 possible ways this business idea can fail.”
Or: “Turn my rough idea into a business plan, website structure, marketing campaign and operating procedure.”
That is knowledge leverage. And we’re only beginning to understand it.
A person who can’t program can increasingly describe what they want and build software.
A person who isn’t a graphic designer can create professional visual concepts.
A mechanic can photograph a component and research how the system operates.
A small business can analyze thousands of transactions without hiring a full-time analyst.
An entrepreneur can examine contracts, research markets, compare equipment, design databases, write procedures and brainstorm products with specialized assistance available almost instantly.
AI doesn’t magically make every idea good. It does something arguably more important:
It dramatically reduces the cost of thinking about an idea.
That means one individual can investigate far more possibilities before committing money and labor.
This fits perfectly with Measure Twice, Cut Once.
Before AI, measuring twice might have required five specialists and $20,000.
Today you might be able to conduct the first 80% of that analysis sitting at your desk.
And then bring in the human specialist for the 20% where expertise, accountability and judgment really matter.
Imagine the Leverage of One Person
Suppose you’re starting a small manufacturing business.
Twenty years ago you might have needed:
An accountant to model your costs.
A programmer to build your inventory system.
A designer to make your advertising.
A copywriter to create your website.
A researcher to analyze competitors.
A consultant to design your workflow.
An IT person to configure your servers.
You may still need professionals for many of those things.
But AI lets one person intelligently participate in all of them.
That’s a profound difference.
You aren’t replacing knowledge.
You’re gaining access to knowledge you previously couldn’t afford to have sitting beside you all day.
And perhaps the biggest opportunity isn’t asking AI to do your work.
It’s asking AI to help you figure out: What work should I be doing in the first place?
That is the ultimate leverage.
The billionaire has always understood that the objective isn’t to personally lift the heaviest rock.
It’s to build the biggest lever.
For the first time in history, ordinary individuals are gaining access to an extraordinarily powerful lever for knowledge, creativity and execution.
The question won’t simply be: “How intelligent are you?”
Increasingly it will be: “How effectively can you leverage intelligence—your own, other people’s, and artificial intelligence—to turn an idea into something real?”
And that may be one of the biggest economic shifts of the AI era.