Think of it as Yoga for the brain, we are going to stretch a bit.
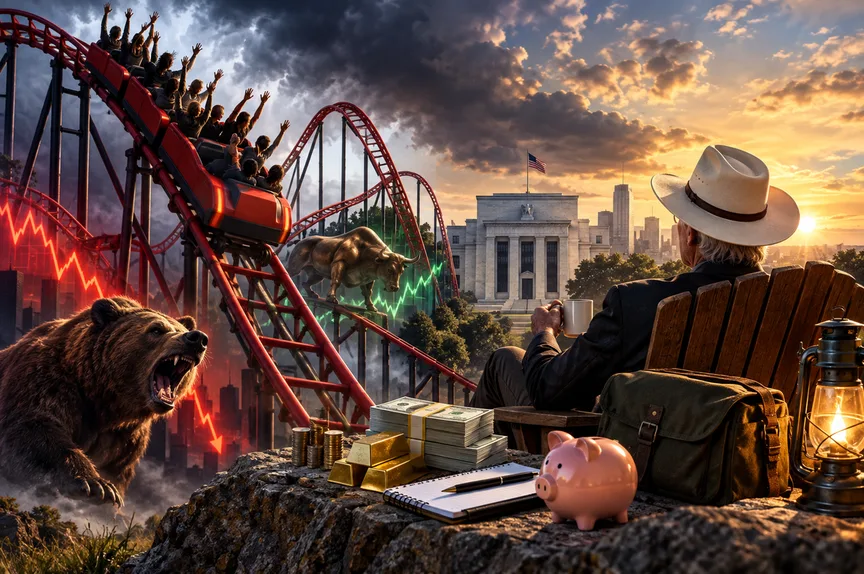
The Market Is a Roller Coaster — Make Sure You Can Afford the Ride
Every penny that you save is a penny earned -- said a wise person somewhere.
Maybe it is time to stop worrying about how much money you can make and start worrying about how financially strong you will be if things get ugly.
Today, Tuesday, September 15, the Federal Reserve begins its two-day meeting. The actual interest-rate announcement comes tomorrow at 2:00 PM Eastern, followed by the Fed press conference at 2:30. And right now, Wall Street is leaning heavily toward a quarter-point rate increase.
A few weeks ago, economists were arguing about whether the Fed would raise rates, lower them, or sit on its hands.
Now the argument has changed.
Inflation has been hotter. Oil is over $100. The 10-year Treasury yield has pushed above 5%. Markets are nervous, and suddenly a rate increase that many people weren’t expecting has become the favorite.
Will the Fed raise rates? Probably.
Could they surprise everybody? Of course.
That’s why they call it a market instead of a schedule.
But here’s the important part: I don’t think the average person should be trying to outguess the Federal Reserve.
I think the average person should be asking a much simpler question: What happens to me if the next three to five years are difficult?
I’ve been around long enough to have seen this movie before.
The actors change. The costumes change. The experts on television change. But the plot is remarkably similar. Everything goes up. Everybody gets confident.
People start believing that whatever went up yesterday will obviously go up tomorrow.
Money gets easy. Debt gets bigger. People buy houses they can barely afford, cars they don’t need, toys they don’t have the cash for and subscriptions they forgot they had.
Then something changes. Maybe interest rates. Maybe oil. Maybe war. Maybe banks. Maybe real estate. Maybe technology. Maybe all of them decide to misbehave at once.
And suddenly everybody discovers that the financial roller coaster has a downhill section.
I Don’t Know If We’re Going to Crash
Let me make something very clear. I am not predicting a market crash.
People who confidently tell you exactly when the market is going to crash usually have one of two things: A newsletter to sell you or a remarkable ability to forget their previous predictions.
Markets don’t send invitations.
They don’t say: Dear Investor,
Please be advised that the bear market will begin next Thursday at 10:17 AM. Kindly liquidate your speculative positions by Wednesday afternoon.
It doesn’t work that way. What I am saying is that there are enough warning lights blinking that I think it makes sense to prepare for a difficult period.
Maybe I’m wrong. I hope I am.
If the market continues higher, wonderful.
But preparing for trouble when times are relatively good is considerably easier than preparing for trouble after it has already arrived.
You buy the fire extinguisher before the kitchen is on fire.
My Number-One Recommendation: Reduce Your Expenses
Forget stocks for a minute. Forget gold. Forget the Fed. Forget CNBC.
Look at your own checkbook. Because your biggest financial risk may not be whether the S&P 500 drops 25%.
Your biggest financial risk may be that your monthly obligations have grown so large that you no longer have room to maneuver.
So here’s what I would be doing: Reduce expenses. Not someday. Now.
Go through everything. Dining out. Subscriptions. Cars. Boats. Hobbies. Vacations. Credit cards. Insurance. Storage units full of things you haven’t looked at since the Obama administration.
That $17 subscription you forgot about. The $80-a-month service that seemed like a wonderful idea when you signed up.
The expensive car you’re making payments on mainly because your neighbor has an expensive car.
I’m not saying go live underneath a bridge and eat canned beans.
I’m saying create financial breathing room. There is an enormous difference.
Because here’s something people forget: A stock market decline does not mean the cost of living declines.
Your portfolio can fall 30% while groceries remain expensive.
Your house can decline in value while your property insurance goes up.
Your retirement account can shrink while your electric bill increases.
Your employer can cut hours while your mortgage stays exactly the same.
Life has no obligation to coordinate its disasters for your convenience.
And that’s what concerns me more than whether the Dow is up or down tomorrow afternoon.
Plan Like You Might Lose Your Job
That sounds pessimistic. I don’t think it is. I think it’s practical.
Ask yourself: If my income disappeared tomorrow, how long could I live exactly the way I’m living today?
One month? Three months? Six months? A year?
That answer tells you more about your financial security than your car, your house or the balance on your brokerage statement.
Plan as though you might become unemployed. If you don’t, fantastic.
Now you have extra money.
If nothing bad happens, your emergency fund didn’t hurt you.
Paying off your credit cards didn’t hurt you.
Reducing your monthly expenses didn’t hurt you.
Having fewer obligations didn’t hurt you.
You simply became financially stronger.
There aren’t many preparations for disaster where being wrong still leaves you better off.
This is one of them.
Debt Is Wonderful — Until It Isn’t
Debt feels cheap when your income is secure.
Debt feels very different when your income becomes uncertain.
A $900 car payment doesn’t seem terrible when you’re making good money.
Lose your job and suddenly you realize you aren’t driving a car.
The car is driving you. Credit-card debt is even worse.
If you’re paying 20-something percent interest on a credit card, I wouldn’t spend a lot of time wondering whether I can make another 8% in the stock market.
There’s a much more obvious fire burning in the kitchen.
Put it out. I’m not against debt. Debt is a tool. Businesses use debt.
Real-estate investors use debt. Governments have apparently become rather fond of it.
But debt reduces flexibility. And if there’s one thing I want going into an uncertain economy, it’s flexibility. Get rid of those credit cards – they are like anchors around your neck.
Cash Isn’t Cowardice
For the last fifteen years or so, investors were repeatedly taught that cash was stupid.
“Cash is trash.” You’ve heard it. If money wasn’t invested somewhere, people felt like they were doing something wrong.
That made a certain amount of sense when cash earned practically nothing.
But that isn’t the world we’re living in today.
There are short-term Treasury instruments paying respectable yields without requiring you to bet that Nvidia, Apple, Tesla or anybody else will be worth more next Tuesday.
For money that I may want to deploy relatively soon, something like SGOV — the iShares 0–3 Month Treasury Bond ETF — interests me.
As of September 10, SGOV’s 30-day SEC yield was about 3.63%, and its effective duration was only about 0.11 years. It is designed around extremely short-term U.S. Treasury securities.
I’m not buying something like SGOV because I expect to become rich from a 3½-percent yield. That’s not the point.
The point is: Dry powder. This is what Warren Buffet does, I did not invent it.
I want money sitting somewhere relatively stable, earning something, and available when opportunities appear.
If the Fed keeps raising rates, newly issued Treasury bills can eventually offer higher yields as SGOV rolls its portfolio.
If the economy rolls over and the Fed eventually cuts rates aggressively, SGOV’s income yield would likely decline as those lower-rate bills replace the old ones.
But because the maturities are so short, it doesn’t have nearly the same interest-rate sensitivity as a long-term bond fund.
I’m not trying to hit a home run with that money. I’m trying to keep the bat in my hands.
Because a Crash Isn’t Just a Disaster
This is where people get emotional.
They look at a market crash as though somebody came into their house and stole the furniture.
If you’re heavily invested and need the money, a crash can certainly feel that way.
But if you’re sitting on cash?
A crash looks different. Suddenly companies you’ve wanted to own for years are cheaper.
Maybe 10% cheaper. Maybe 20%. Maybe 40%. Sometimes much more.
The same stock everybody loved at $200 becomes “too dangerous” at $120.
Human beings are funny that way.
We love buying shirts when they’re 40% off.
We love buying televisions when they’re 30% off.
Put a 30%-off sign on a steak and people fight over it.
But put the stock market 30% off and everybody runs out of the store screaming.
That’s why liquidity matters.
I Wouldn’t Try to Pick the Bottom
I’ve never met anybody who could consistently ring the bell at the exact bottom of a bear market.
Plenty of people have discovered the bottom afterward.
They’re extraordinarily talented at that. So if markets start falling, I wouldn’t dump every available dollar in because stocks dropped 10%.
I’d buy in stages.
Maybe deploy some money after a meaningful correction.
A little more if it falls further.
More if valuations become genuinely attractive.
More again if fear becomes extreme and the businesses I’m buying remain fundamentally sound.
The exact percentages aren’t important. The plan is important.
Because the worst time to develop an investment strategy is while the television is screaming:
MARKETS PLUNGE and your portfolio has lost more money before breakfast than you earned all month.
That’s when emotion takes over. People sell because they’re scared.
Then they wait. And wait. And wait.
They tell themselves: “I’ll get back in when things settle down.”
Of course, by the time things “settle down,” the market may be 20% higher.
That’s the little joke Wall Street has been playing on human psychology for about two hundred years.
Volatility Creates Opportunity
People misunderstand what I mean when I say I like volatility.
I’m not saying I enjoy losing money.
I’m saying that large differences between price and value create opportunity.
If everything goes straight up forever, eventually everybody knows what everybody else knows.
The bargains disappear. But fear creates strange pricing.
Greed creates strange pricing too. That’s where the contrarian has an advantage.
Not because contrarians are automatically right.
Being different from everybody else is not the same thing as being intelligent.
Sometimes the crowd is right and the contrarian is just the fellow walking southbound on a northbound interstate.
The trick is having enough discipline to recognize when fear has pushed good assets below reasonable value — and enough cash to do something about it.
That’s why I’m preparing now.
What About Gold?
I own no crystal ball for gold either – Gold has historically served as a store of value and can play a role when investors are worried about inflation, currency debasement, fiscal problems or geopolitical risk.
But gold is not magic. It goes up. It goes down.
Sometimes it does absolutely nothing for years while everybody who predicted $10,000 gold quietly finds another subject to talk about.
I wouldn’t build my entire financial life around gold any more than I would build it around one technology stock.
But as part of a diversified strategy? Absolutely worth considering.
Especially in a world where governments have rediscovered the ancient political art of spending more money than they collect.
The Bigger Question Isn’t Tomorrow’s Fed Decision
Everybody will watch the Fed tomorrow.
They’ll parse every word. Did he say “persistent”?
Did he say “balanced”?
Did he say “uncertainty”?
Somebody on television will explain that moving his left eyebrow at 2:37 PM was clearly hawkish.
Algorithms will trade billions of dollars before most of us finish reading the first paragraph of the announcement.
Fine. Let Wall Street play that game.
The question I’m asking is much more personal: What position do I want to be in if the next few years are difficult?
I want lower expenses. I want less high-interest debt. I want cash.
I want liquidity. I want investments I understand.
I want the ability to survive without selling good assets at terrible prices.
And most importantly: I want the ability to buy when everybody else is afraid.
That is financial strength.
Think Three to Five Years, Not Three to Five Days
This isn’t really a story about tomorrow’s interest-rate decision.
Tomorrow’s Fed announcement is simply a reminder.
Economic cycles still exist. Bull markets still end. Bear markets still end. Interest rates rise and fall. Oil rises and falls. Politicians promise. Economists forecast. Wall Street predicts.
And ordinary people still have to pay the electric bill on Friday.
So I’m thinking three to five years ahead.
What unnecessary expenses can I eliminate?
What debts can I pay off?
How much emergency cash can I accumulate?
What assets do I really want to own if they become significantly cheaper?
What investments do I own today simply because everybody else owns them?
And if I lost part of my income tomorrow, what would I wish I had done today?
Those are much more important questions to me than guessing whether the Dow will be green or red at 4:00.
Every Dollar You Don’t Spend Is Working for You
There’s an old saying that a penny saved is a penny earned.
Actually, it’s better than that.
The dollar you don’t spend doesn’t have to be earned again.
You don’t need overtime to replace it.
You don’t need investment returns to recover it.
You don’t need to pay interest because you borrowed it.
You don’t need to pay income tax on money you never needed to earn in the first place.
Cutting recurring expenses permanently changes the mathematics of your life.
Save $500 a month and that’s $6,000 a year.
That’s $30,000 over five years before counting any investment return at all.
That’s real money.
And more importantly, it’s freedom money.
Money that allows you to say no. Money that allows you to survive. Money that allows you to wait. Money that allows you to invest when somebody else can’t.
So That’s My Plan
I’m not heading for a bunker. I’m not selling everything.
I’m not predicting the Great Depression.
I’m certainly not going to spend tomorrow afternoon staring at a television and trying to trade every sentence coming out of the Federal Reserve.
I’m doing something much less exciting. I’m reducing expenses.
I’m paying attention to debt. I’m keeping some short-term money liquid.
I’m considering short-term Treasuries for money I don’t want exposed to stock-market volatility.
I’m keeping an eye on gold and other assets.
I’m making a list of companies I’d love to own at considerably lower prices.
And I’m preparing myself psychologically for the possibility that markets don’t always go up.
If I’m wrong and the bull market runs another five years? Fine.
I made a little less money on the portion I kept conservative. I can live with that.
But if we’re heading toward a long bear market, recession or financial accident?
I’ll be glad I didn’t wait until everybody else started worrying.
Because by then, preparation gets expensive.
Reflections
Everybody wants to know when the market will crash.
That’s probably the wrong question.
Ask instead: “If it crashes, will I be one of the people desperate to sell — or one of the people financially strong enough to buy?”
Bull markets reward optimism.
Bear markets reward preparation.
And panic has always been considerably more expensive than patience.
So reduce the bills you don’t need.
Pay off the debt that’s eating you alive.
Keep some powder dry.
Don’t gamble money you may need next month.
And remember something Wall Street occasionally forgets:
Sometimes the smartest investment you can make isn’t buying something.
It’s making sure you don’t have to sell anything when everybody else does.
And Remember “Every penny that you save is a penny earned” and that never changes.