Think of it as Yoga for the brain, we are going to stretch a bit.
The End is Near… if you are T-MOBILE, AT&T, Verizon
A corporation will tell you competition is healthy right up until somebody competes with it. Then, quite suddenly, it becomes a matter for the regulators. --YNOT!
For years, America’s wireless giants have offered us the magnificent freedom to choose which company will confuse us, raise our bill, and explain that the price advertised on television applies to a family of four with six lines, three trade-ins, automatic payments, and a favorable alignment of Jupiter.
Then, after we spend an afternoon switching providers, we discover we have escaped one plantation of fine print and arrived at another.
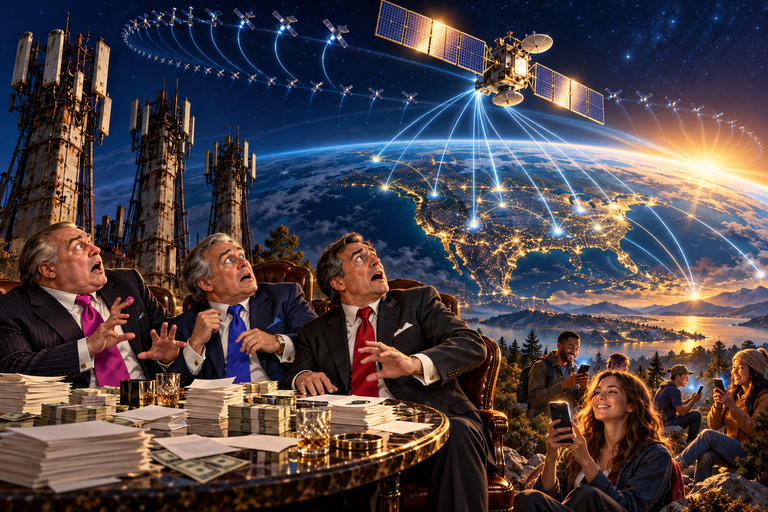
Now something interesting is approaching from above. Starlink.
And if SpaceX follows through on its ambitions, T-Mobile, AT&T, and Verizon could discover that the most frightening words in American business are not “congressional investigation.”
They are: “Your customer has another option.”
Am I announcing the funeral of the big three?
Not yet. These companies have enormous networks, millions of customers, deep pockets, and considerable experience surviving things that should have embarrassed them into retirement.
But I would suggest they postpone ordering the anniversary cake.
Someone is looking at their business.
And he brought rockets. The fourth chair at the table
The important development is bigger than sending an emergency text from a mountain.
SpaceX has agreed to acquire Grain Management’s nationwide 800 MHz spectrum portfolio, with the announced aim of supporting Starlink Mobile service from both the ground and space. That is a substantial signal of intent, although an agreement and a fully operating network remain different milestones.
The distinction matters. A satellite feature that helps an existing carrier fill a coverage gap is one thing.
A company assembling the ingredients to compete for your monthly phone bill is another.
One is a helpful guest. The other is measuring the dining room.
For the established carriers, satellite connectivity can be a pleasant partnership so long as it makes their existing business more attractive. The conversation becomes less pleasant when the partner begins considering a business of its own.
There is a considerable difference between inviting someone aboard your ship and discovering he has arrived with blueprints for a better one.
The paperwork matters—even when the headline is exciting
The source material celebrates an FCC development involving 482 megahertz of additional spectrum as though Washington has handed Elon Musk the keys to every carrier’s network.
That gets ahead of the paperwork.
The official October 29 meeting agenda described a proposed rulemaking to expand the spectrum eligible for supplemental coverage from space. Opening a rulemaking is a step toward changing the rules; it is not, by itself, a completed nationwide license or unrestricted permission to use another company’s airwaves.
Washington has a talent for making the opening of a door resemble the completion of a railroad.
Still, doors matter.
Especially when the people already inside the building have enjoyed charging admission.
The broader direction is what interests me: the boundary between satellite service and conventional wireless service is becoming a business opportunity.
And business opportunities have a nasty habit of disturbing comfortable arrangements.
Your kitchen remains an engineering problem
There is, however, an obstacle that enthusiasm cannot repeal. Your house.
A satellite connection that works beneath an open sky does not automatically deliver excellent service through a roof, concrete walls, coated windows, and the parking garage beneath your office.
The modern consumer has unreasonable expectations of a telephone. We expect it to work in the kitchen, at the grocery store, and occasionally in the very building where the carrier sold it to us.
This is why the ground network matters.
Reporting says SpaceX has explored access to at least 80,000 U.S. cell sites, with Crown Castle among the companies involved in talks. These are reported discussions, not a completed nationwide deployment. But they suggest an ambition that extends well beyond occasional satellite messaging.
The compelling possibility is a combined system: towers where towers work well, satellites where the ground network runs out.
That would be a serious proposition.
The customer does not need to know whether the connection came through an antenna on a water tower or a spacecraft passing overhead.
The customer needs the call to stay connected.
Preferably while asking why the bill increased.
The bill is where the revolution gets personal
People do not generally wake up angry about spectrum allocation.
They wake up angry about paying more for something that appears to work exactly as it did last year.
They are tired of promotions that expire, discounts that disappear, and charges with names suggesting they were invented by a committee whose members were paid by the syllable.
They are tired of “unlimited” requiring an explanation.
Unlimited should be a word you can understand without opening a second browser tab.
And they are tired of cancellation procedures that make joining a service feel like buying a sandwich and leaving it feel like negotiating a prisoner exchange.
A company can spend a fortune advertising customer loyalty.
It can also try making the customer want to stay.
That second approach seems to receive less attention.
A credible fourth competitor would give the established carriers a reason to rediscover it.
Competition has a remarkable effect on corporate hearing
There are complaints a company cannot seem to hear for years.
Then a competitor arrives, and suddenly management hears them from three counties away.
Prices become flexible. Plans become simpler.
Longstanding technical limitations become solvable.
The same customer who spent forty minutes being told nothing could be done receives a retention offer before finishing the sentence, “I’m switching.”
Apparently the problem was never entirely technological.
Sometimes the missing ingredient is fear.
That is why I welcome the possibility of another serious wireless competitor. Even customers who never sign up could benefit if the established carriers have to work harder to keep them.
A better deal does not always begin with a company becoming generous.
Sometimes it begins with the company becoming nervous.
Then there is the landlord. The tower side of this story deserves attention, too.
Tower companies own infrastructure that wireless operators rent to install their equipment. A major new network could mean another tenant, additional leasing activity, and a fresh source of demand.
Crown Castle has attracted particular interest because it was named in reporting about SpaceX’s discussions.
Now comes the more entertaining speculation: what if SpaceX eventually wanted to buy a tower company rather than simply rent space?
It is an interesting thought.
A conversation about leasing towers is not evidence of an agreement to acquire the landlord. Somewhere between those two ideas, a great many stock-market stories learn to fly without wings.
A hypothetical acquisition could create the delicious situation of established carriers renting infrastructure from an ambitious new rival.
I appreciate the irony.
But irony is not a signed merger agreement.
And a predicted buyout premium is not money in your account.
Do not let a good story pick your pocket
The investment pitch practically writes itself.
Elon needs towers. A tower company owns towers. Therefore, buy the tower company and wait for the check.
Unfortunately, the stock market has buried many perfectly logical sentences.
A lease might happen. An acquisition might never happen. Deployment could take longer, cost more, or develop differently than expected. Existing debt, customer concentration, financing costs, and the price paid for the shares still matter.
A dividend is a business decision, not a promise from heaven.
And “Elon might buy it” is a possibility, not a valuation method.
The source material moves too easily from an interesting business thesis to confidence about a large, immediate payout.
I would keep the interesting thesis and leave the crystal ball with whoever sold it.
There may be an opportunity here.
There is certainly a story.
The two should not be confused.
Elon does not have to be your favorite person
Some readers will dismiss the whole prospect because they dislike Musk.
Others will assume success because they admire him.
Neither position tells us whether the service will work inside the house.
My standard is less theatrical.
Does it provide reliable coverage? Is the price competitive? Are the terms understandable? Can I cancel without producing a blood sample and the original receipt for my birth?
If Starlink delivers, I will consider it.
If T-Mobile, AT&T, or Verizon respond with better service and fairer pricing, I will consider that, too.
My loyalty is available on a month-to-month basis.
Corporate America taught me the arrangement.
The big three still have a choice
The established carriers are capable competitors. They can invest, improve their networks, build partnerships, simplify their offers, and make customers happier.
That is precisely what I would like to see.
But a company that dismisses a challenger because the challenger has not yet reproduced every feature of its business may be studying the wrong moment.
The important question is what that challenger is assembling—and whether customers are eager for it.
There is a sizable audience for a phone company that offers a clear bill, dependable service, and an uncomplicated exit.
It is remarkable how revolutionary those modest requests can sound.
So, is the end near?
For T-Mobile, AT&T, and Verizon as functioning businesses?
I would not order the flowers yet.
For the comfortable assumption that American wireless customers will keep circulating among the same three major networks, complaining all the way?
That assumption deserves a much closer look.
SpaceX still has to execute. Agreements must become infrastructure. Infrastructure must become dependable service. Dependable service must become something people will pay for and recommend.
Rockets do not exempt anyone from customer support.
But the possibility of serious new competition is enough to make this worth watching.
Because the most useful thing Starlink could deliver from space may be a little urgency to the executives on the ground.
T-Mobile, AT&T, Verizon: your customers are looking up.
You might want to give them a reason to look back.
Disclaimer: This post reflects my opinions and includes speculation about future competition, business deals, and potential acquisitions. I do not own Starlink or SpaceX shares, but I did purchase shares of Crown Castle (NYSE: CCI), so I have a financial interest in CCI’s performance. No SpaceX–Crown Castle acquisition is confirmed, and neither a buyout nor an investment return is guaranteed. This is commentary, not investment advice. Do your own research before investing.