Think of it as Yoga for the brain, we are going to stretch a bit.
The Cruise to Nowhere… An Unfortunate Business Venture or a Ponzi Scheme?
Before buying a home on the water, make certain the business plan can float. -- YNOT!
There is something particularly cruel about selling somebody a retirement dream and then giving them until two in the afternoon to pack it into a suitcase.
A canceled vacation is an inconvenience. Losing access to the place you call home, in a foreign country, after committing a substantial portion of your savings is something else entirely.
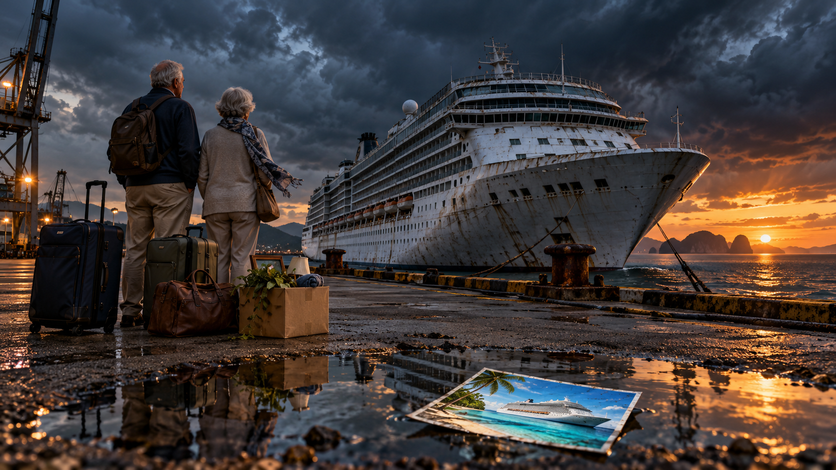
Residents aboard Villa Vie Odyssey have found themselves confronting precisely that distinction. On October 26, they were instructed to disembark in Sihanoukville, Cambodia, after the company said it could not secure the fuel necessary to continue operating. Reuters reported that the morning notice gave residents until 2 p.m. to leave, with arrangements available for those unable to remove everything in time.
The itinerary apparently contained one destination that never made it into the brochure: financial uncertainty.
And now comes the question that deserves a careful answer:
Was this an ambitious business overwhelmed by its expenses, a venture built on unrealistic assumptions, or something that warrants investigation for financial deception?
Those possibilities are different. The people holding the receipts deserve to know which one they bought.
A home with a disappearing horizon
The attraction of residential cruising is easy to understand.
Sell the house. Stop mowing the lawn. Trade traffic for ocean views. Unpack once and let the world come to you.
For retirees who have spent decades working, raising families, paying mortgages, and putting off their own adventures, that is a powerful proposition.
There is nothing foolish about wanting it.
But the more life a customer reorganizes around a promise, the more responsibility the seller assumes for explaining its risks.
A company selling a week at sea needs to deliver a week at sea. A company encouraging people to make a ship their long-term home is asking for a much deeper kind of trust.
The customer may be buying a cabin arrangement. Emotionally, they are buying the belief that somebody has done the arithmetic.
The ocean view is optional. The arithmetic is not.
Fuel prices are an explanation. They are not the whole examination.
Villa Vie attributes the suspension to extraordinary fuel costs. According to its public statement, equivalent monthly fuel expenses rose from approximately $1,800 per cabin to an estimated $6,000–$8,000 in parts of Asia. The company says it slowed its itinerary and spent longer in port, but could not absorb the resulting losses or realistically pass the full increases to residents. It is pursuing restructuring and recapitalization, with no assured outcome.
Those are substantial increases. A serious price shock can damage even a legitimate, competently managed business.
But acknowledging the shock does not end the inquiry.
What assumptions supported the original pricing? What reserves existed? How much room was there for maintenance surprises, weaker cabin sales, or prolonged increases in operating costs?
A financial forecast covering years of residential cruising ought to contain more than a sunny weather symbol and the phrase “hopefully nothing happens.”
Ships require fuel. Machinery wears out. Ports charge money. International events interfere with international travel.
Management cannot predict every crisis. It can explain what protection it built against one.
Fuel hedging might be part of that discussion, but it is no magic shield: it has costs, limits, and risks of its own. The broader question is whether management had a credible combination of reserves, financing, pricing flexibility, and contingency plans.
If the answer was simply that more money would arrive somehow, residents deserve to know when that became the plan.
When the passengers become the bank
The reported emergency financing requests deserve particular scrutiny.
Cruise Industry News says it reviewed an April letter seeking $3 million from residents through an emergency loan opportunity. The offered terms included annual interest of 12%–24%, monthly interest payments, and repayment of principal after twelve months. The publication could not determine whether the requested funds were raised. It also reported a later $360,000 fuel funding request, based on sources aboard.
Twenty-four percent is a remarkable number to offer people whose accommodation depends on your ability to keep buying diesel.
It does not prove fraud. It certainly demands an explanation.
If a company borrowed the full $3 million at 24% annual interest, the interest alone would be $720,000 for the year—before repaying the principal.
What improvement in revenue, reduction in expenses, asset sale, or outside investment was supposed to produce that repayment?
A high interest rate can compensate a lender for taking a high risk. It cannot manufacture the money needed to repay them.
And residents are in an unusually difficult position. They may be evaluating a loan while fearing that refusing to lend could jeopardize their home.
That is a powerful emotional pressure, whether anybody intended to create it or not.
The question becomes painfully personal: Do I risk more money to protect the money I have already committed?
Hope is an expensive financial adviser.
So, was it a Ponzi scheme?
The word deserves more discipline than the internet usually gives it.
A Ponzi scheme involves using incoming investors’ money to pay purported returns to earlier investors while misrepresenting the source or reality of those returns.
A company losing money, borrowing at high interest, seeking investors, or collapsing is not automatically a Ponzi scheme.
Nor does using customer revenue to pay operating expenses establish one. Ordinary businesses do that every day.
The important questions concern representations, obligations, and the actual movement of money.
Were returns ever paid from fresh investment rather than the activity supposedly generating them? Were buyers and lenders given an accurate picture of the company’s finances? Did management know that its promises depended on assumptions it could no longer reasonably defend?
There is also a broader business question that does not require a criminal label:
Could the operation support its existing commitments without continually selling new promises?
That question can expose an unsustainable model even where no Ponzi scheme exists.
On the evidence presented here, I cannot conclude that Villa Vie operated a Ponzi scheme.
I can conclude that residents deserve financial transparency sufficient to answer the question.
Calling something a scam is easy. Following the money is the useful part.
Where did the money go?
The next presentation residents receive should contain fewer horizons and more reconciled accounts.
Where did the original cabin payments go? How much funded the vessel and its preparation? How much covered operating losses, marketing, commissions, management compensation, or other commitments?
What liabilities existed when residents were asked to lend more?
What financial information did prospective buyers receive?
And what, exactly, did a cabin purchase legally provide?
A contractual right to occupy a cabin is not necessarily the same thing as owning real estate, holding equity in the vessel, or having a secured claim against an asset.
The contracts matter. The ownership structure matters. Any existing security interests matter.
If the ship changes hands, what survives? If restructuring fails, what can residents recover?
Nobody should have to discover the meaning of “ownership” for the first time while standing beside their luggage.
The founder’s history is relevant—with the dates attached
Founder Mikael Petterson previously served as managing director of Life at Sea Cruises. He and other team members left in May 2023 amid disagreements with Miray, months before that venture canceled its planned voyage in November after failing to obtain a ship. CNN’s subsequent reporting also described a defamation dispute that Miray later dismissed.
That history does not make him responsible for every decision Life at Sea made after his departure. It does make questions about lessons learned entirely reasonable.
What safeguards did the new venture adopt? What risks had the earlier experience exposed? How did Villa Vie protect residents against the consequences of financing falling through?
Entrepreneurship requires optimism. Stewardship requires knowing when optimism has stopped being a forecast.
Petterson has acknowledged the distress and described efforts to find a solution. Reporting also records his account that higher fuel prices and a failed investment deal contributed to the suspension. Those explanations belong in the story alongside the residents’ losses and unanswered questions.
An apology can begin accountability. It cannot substitute for the accounts.
Do not confuse the customers’ hope with stupidity
There will inevitably be people saying the residents should have known better.
That is a comfortable judgment to make from a home nobody has just asked you to vacate.
People buy into businesses because they believe the people operating them understand the business. They expect disclosed risks, honest representations, and a reasonable foundation beneath the sales pitch.
Wanting an unconventional retirement does not make somebody responsible for another person’s financial planning.
Some residents may still value their time aboard. Meaningful friendships and extraordinary experiences do not disappear because the company encounters a crisis.
But neither do those memories settle the financial questions.
A wonderful dinner does not excuse an unexplained bill for the restaurant.
And the crew deserve consideration too. They have livelihoods, families, and obligations of their own. Whatever the eventual findings, the consequences reach well beyond the executive office.
The next destination should be disclosure
I hope a workable solution exists.
But a rescue should be assessed by what it delivers: safe accommodation, clear communication, documented financing, fair treatment of residents and crew, and obligations the reorganized business can actually meet.
Another announcement that an investor might be interested is not the same thing as money in the bank.
Before residents are asked to commit another dollar, they should have enough independently examined information to judge what that dollar is buying.
Was this an unfortunate venture overwhelmed by extraordinary conditions? Was it undercapitalized and badly managed? Were material risks concealed? Did any conduct cross into fraud?
Those answers require documents and investigation.
They do not require the public to stop asking.
People were sold the freedom to stop worrying about where they would live next. Now that is precisely what some of them have to worry about.
The ship may eventually sail again.
Trust will need considerably more than fuel.
—–
Editorial note: This commentary distinguishes reported events, company explanations, and opinion. Financial distress and emergency borrowing do not, by themselves, establish a Ponzi scheme or other fraud. The circumstances remain developing.