Think of it as Yoga for the brain, we are going to stretch a bit.
RICH vs. POOR — THE POVERTY OF THE MIND
Being poor is not a character flaw. Being rich is not proof of intelligence. But how you think about money can determine how long you keep it. -- YNOT!
There is an old saying that money cannot buy happiness. This is generally repeated by people who have enough money to have tested the theory.
The fellow struggling to pay his electric bill might have a different opinion.
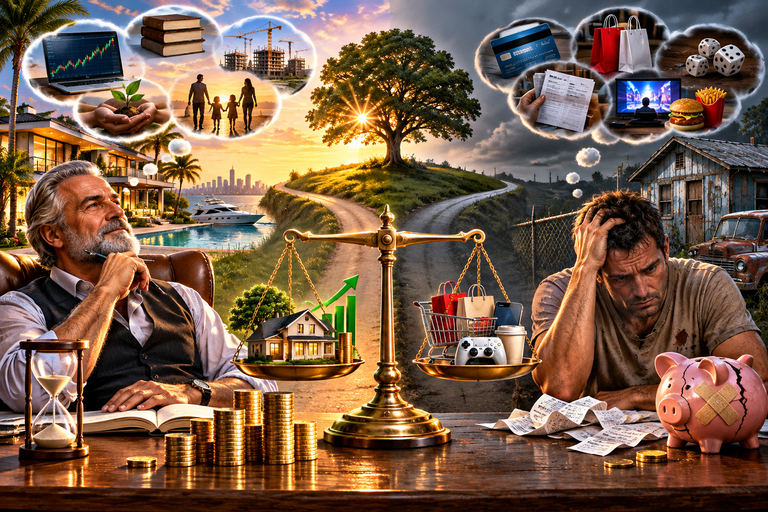
But there is something worth considering in the endless debate about the rich and the poor. It isn’t simply how much money people have. It is how they think about money, what they do with it, and, perhaps most importantly, what they expect money to do for them.
The rich supposedly think differently from the poor. Perhaps they do.
But before we congratulate the rich on their wisdom and condemn the poor for their foolishness, we should remember that some people are born on third base and spend their entire lives congratulating themselves for hitting a triple.
And others are born outside the stadium, trying to figure out how to afford a ticket.
Nevertheless, there are lessons worth learning.
THE FUTURE IS EXPENSIVE, BUT IGNORING IT COSTS MORE
The wealthy are often credited with thinking long-term. They invest today for a tomorrow they expect to arrive.
The financially undisciplined tend to spend today as though tomorrow were somebody else’s problem.
One plants a tree. The other buys a hammock and wonders why there is no shade.
Of course, thinking about retirement is considerably easier when you aren’t worried about next Friday’s rent.
But the principle remains.
Wealth is often built by postponing a little pleasure today to purchase a great deal more freedom tomorrow. Delayed gratification is the name of this skill.
The difficulty is convincing people that tomorrow deserves a vote in today’s spending decisions.
OPPORTUNITY AND PROBLEMS OFTEN WEAR THE SAME CLOTHES
Show two people the same problem. One sees an obstacle. The other sees a business.
A broken fence is an inconvenience to the homeowner and an opportunity to the carpenter.
A shortage of housing is a crisis for families and an opportunity for builders.
A problem worth solving is frequently a business waiting to be invented.
The entrepreneur asks, “How can I make this better?”
The pessimist asks, “Why does this always happen to me?”
One question opens doors. The other makes a comfortable chair out of disappointment.
But opportunity also requires resources, timing, access, and sometimes plain old luck.
An excellent idea without the means to execute it is like owning a winning lottery ticket in a country where nobody sells lottery tickets.
MONEY IS A TERRIBLE SERVANT WHEN YOU LET IT BECOME YOUR MASTER
There are people who earn $50,000 a year and manage to save something.
There are people who earn $500,000 a year and somehow manage to owe everybody.
The difference is not always intelligence. Sometimes it is arithmetic.
A budget is not a punishment. It is a declaration that you, rather than your impulses, will decide where your money goes.
But modern society has perfected the art of convincing people to purchase things they don’t need, with money they haven’t earned, to impress people they don’t particularly like.
We have invented a remarkable economy in which nearly everything can be financed except common sense.
The credit card has become a magician’s wand. Wave it today, and tomorrow’s paycheck disappears.
It is not what you earn that makes you wealthy. It is what you earn, what you keep, and what you do with what remains.
Although, naturally, you must first earn enough to have something remaining.
THE RICH TAKE RISKS. THE FOOLISH TAKE CHANCES.
There is an enormous difference between investing and gambling.
The investor studies the business. The gambler studies the color of the dice.
The investor calculates what can go wrong. The gambler calculates how much he will spend when everything goes right.
The investor knows that losing is possible. The gambler believes losing is something that happens to other people.
And then there is the fellow who buys a cryptocurrency because a stranger on the internet assured him it would make him a millionaire by Thursday.
By Friday, he has acquired a valuable education. Unfortunately, it cost him his savings.
The goal is not to avoid risk. It is to understand risk well enough that failure does not destroy your ability to try again.
Fortunes have been made by taking intelligent risks.
And fortunes have been lost by confusing confidence with competence.
EDUCATION IS NOT WHAT YOU KNOW. IT IS WHAT YOU ARE WILLING TO LEARN.
Some people graduate from college and never learn another thing.
Others leave school early and spend the rest of their lives educating themselves.
T he difference is curiosity. The world changes. Industries disappear. Technologies emerge. Entire professions become obsolete while new ones are invented.
Artificial intelligence is presently demonstrating this lesson with considerable enthusiasm.
The fellow who believes he has learned everything necessary for success is preparing himself for a world that no longer exists.
The successful person understands that yesterday’s knowledge has an expiration date.
The foolish person insists that yesterday’s answers must still be correct because he has grown comfortable repeating them.
Ignorance is not necessarily a lack of education. Sometimes it is the stubborn refusal to update one.
And that condition is distributed quite generously among both rich and poor.
ONE SOURCE OF INCOME IS A COMFORTABLE PLACE TO LIVE — UNTIL THE ROOF COLLAPSES
There was a time when a man could work for one company for forty years, collect a pension, and retire with a gold watch.
Today, he is fortunate if the company lasts forty months without announcing a restructuring.
Depending entirely on a single paycheck can be dangerous.
Businesses fail. Jobs disappear. Economies change.
The wealthy often own assets that generate income independently of their daily labor.
Businesses, investments, real estate, royalties, and other productive assets can provide financial resilience.
But multiple income streams are not magic.
Owning five failing businesses does not make you financially diversified. It makes you exceptionally busy losing money.
And telling someone working two jobs to start a third business is advice that generally sounds better from a yacht.
The real objective is not to work every waking hour.
It is to build enough financial independence that eventually you do not have to.
Money should ultimately purchase time, not consume every minute of it.
DISCIPLINE IS BORING. THAT IS WHY IT WORKS.
Nobody wants to hear that building wealth generally involves years of ordinary decisions.
Saving regularly. Avoiding unnecessary debt. Investing consistently. Learning from mistakes. Living below your means when possible.
And resisting the irresistible temptation to purchase a $90,000 automobile to demonstrate to strangers that you are successful.
There is no excitement in compound interest.
It does not dance on television. It does not promise a fortune by next Tuesday.
It simply continues working while people chase the latest opportunity to become rich without doing anything particularly useful.
Discipline rarely makes headlines. Bankruptcy frequently does.
The tragedy is that people often prefer the excitement of appearing wealthy to the boredom of becoming financially secure.
BUT HERE IS WHERE THE FAIRY TALE GETS COMPLICATED
The illustration comparing rich and poor mindsets makes some worthwhile observations.
But it also commits a common intellectual crime. It mistakes correlation for causation.
Not everyone is poor because they think poorly. And not everyone is rich because they think brilliantly. Some people inherit millions. Some inherit debts. Some begin life surrounded by opportunities. Others begin life surrounded by obstacles.
Some work extraordinary hours simply to survive.
Others collect extraordinary returns from money they never personally earned.
A wealthy fool can remain wealthy for decades. A brilliant poor person can struggle for a lifetime. Medical expenses, disability, family obligations, economic recessions, discrimination, and plain bad luck do not disappear because someone reads a motivational book.
The world is not an equal playing field. And pretending otherwise doesn’t make it one.
But neither does inequality eliminate individual responsibility.
Two things can be true simultaneously: the system can be unfair, and your decisions can still make a difference.
That is the uncomfortable truth that both political camps frequently prefer to ignore.
One side suggests that poverty is almost entirely the fault of the individual.
The other sometimes suggests that individual choices barely matter at all.
Both explanations are convenient. Neither is complete.
THE REAL DIVIDE IS NOT ALWAYS BETWEEN RICH AND POOR
It is often between those who understand how money works and those who don’t.
Between those who distinguish an asset from a liability.
Between those who build something of lasting value and those who continually purchase the appearance of value.
Between people who accept that their circumstances can change and people who assume their circumstances never will.
But perhaps the greatest difference is this:
Some people work for money their entire lives. Others eventually learn how to make money work for them.
And the truly fortunate discover that there are things more valuable than money.
Time. Health. Family. Friendship. Freedom.
A person can possess millions and be miserable.
Another can possess very little and live a remarkably satisfying life.
Wealth and happiness are not synonyms, although poverty has a rather impressive talent for making happiness harder to maintain.
MONEY IS A TOOL, NOT A MEASURE OF HUMAN WORTH
You cannot think yourself into becoming a millionaire any more than you can think yourself into becoming seven feet tall.
Positive thinking does not pay the mortgage.
Discipline cannot manufacture opportunities that do not exist.
And no amount of financial education can make $2,000 pay $3,000 worth of bills.
But good decisions, financial knowledge, patience, adaptability, and calculated risk-taking can improve your chances of building a better future.
The purpose of developing a better financial mindset is not to imitate wealthy people.
It is to understand the principles that allow wealth to be created, preserved, and used intelligently.
And perhaps to avoid the mistakes that allow it to disappear.
For there is one thing more foolish than being poor and pretending to be rich.
It is being rich and believing that your bank balance makes you wise.
The world has produced an abundance of wealthy idiots and impoverished geniuses.
Money does not cure stupidity. It merely allows stupidity to travel first class.
And that, my friends, may be the most expensive lesson of all.